 Anahita Attarian
Oman corporate tax is generally charged at 15% of net taxable income for institutions and commercial companies. A lower 3% rate can apply to qualifying small enterprises under specific conditions, while oil and gas exploration companies may be taxed at 55% based on concession arrangements. Companies operating in Oman must register with the Tax Authority, file income tax returns electronically, keep accounting records, and pay tax by the statutory deadline. For expats and foreign investors, the key point is that company registration, tax registration, VAT, withholding tax, free-zone incentives, and personal income tax are separate issues and should not be confused.
What Is the Corporate Tax Rate in Oman?
The standard Oman corporate tax rate is 15% of net taxable income for institutions and commercial companies. The Oman Tax Authority also lists a 3% rate for small enterprises that meet specific conditions, such as revenue and employee-related requirements. Oil and gas exploration companies are listed separately at 55% income tax, based on concession contracts with the government.
This means most normal LLCs, branches, foreign-owned companies, trading companies, consulting companies, and service businesses should plan around the 15% corporate income tax rate unless they clearly qualify for a special regime, small-enterprise rate, free-zone exemption, or sector-specific treatment.
Oman Corporate Tax: Quick Summary
Tax Area | Main Rule |
|---|---|
Standard corporate income tax | 15% of net taxable income |
Small enterprise rate | 3% if specific conditions are met |
Oil and gas exploration | 55%, based on concession contracts |
Tax registration | Mandatory within 60 days from start of activity or registration |
Tax return filing | Electronically, generally within 4 months after year-end |
Late payment | Additional tax of 1% per month on unpaid tax |
VAT standard rate | 5% |
VAT mandatory registration threshold | OMR 38,500 taxable supplies |
VAT voluntary registration threshold | OMR 19,250 taxable supplies |
Withholding tax | 10% on certain payments to non-residents without a permanent establishment |
Free zones | May offer tax exemptions, but compliance still applies |
Personal income tax | Separate law starts in 2028 for individuals above OMR 42,000 annual income |
Oman is not a zero-corporate-tax jurisdiction. It has a clear corporate tax system, but the rate is predictable for most businesses.
Who Pays Corporate Tax in Oman?
Corporate tax in Oman applies to businesses carrying on taxable activity in the country. This includes Omani companies, foreign-owned companies registered in Oman, branches of foreign companies, permanent establishments, and commercial entities earning taxable income through Oman.
PwC’s 2026 Oman tax summary explains that Oman taxes the worldwide income of entities formed in Oman and the Oman-source income of branches and other permanent establishments.
Entities that may fall under Oman corporate tax include:
Limited liability companies
Joint-stock companies
Foreign company branches
Permanent establishments
Partnerships carrying on business
Commercial establishments
Free-zone companies, unless exempted under approved rules
Professional service firms
Trading companies
Consulting companies
Industrial companies
Import-export businesses
Real estate operating companies
Contractors and subcontractors
A company does not avoid corporate tax simply because it is foreign-owned or newly registered.
Corporate Tax for Foreign-Owned Companies
Foreign-owned companies in Oman are generally subject to the same standard corporate income tax framework as local companies. The main question is not whether the shareholder is Omani or foreign; it is whether the entity has taxable income under Oman’s tax rules.
A foreign investor who registers an LLC in Oman should expect to handle:
Tax Authority registration
Accounting records
Annual income tax return
Tax payment
VAT registration if threshold is reached
Withholding tax obligations on some foreign payments
Proper invoices and expense documentation
Bank and source-of-funds compliance
Audited accounts where applicable
Tax clearance or status certificates when required
Oman allows foreign investors to establish companies in many sectors, but foreign ownership does not remove tax obligations.
Corporate Tax for LLCs in Oman
The LLC is the default vehicle here, much as it is next door - see LLC Company Formation in the UAE for the structural comparison. An LLC is one of the most common company forms used by expats and foreign investors in Oman. An LLC is normally subject to the standard 15% corporate income tax on taxable profits, unless it qualifies for the small-enterprise rate or another special treatment.
For an Oman LLC, the tax calculation is generally based on:
Business revenue
Deductible business expenses
Accounting profit adjustments
Tax depreciation
Non-deductible expenses
Carried-forward losses, if available
Related-party transactions
Withholding tax treatment
VAT treatment, if registered
A new LLC should not wait until the first profit year to think about tax. Registration, bookkeeping, invoices, contracts, and bank records should be structured correctly from the first month.
Small Enterprise Corporate Tax Rate in Oman
Oman’s Tax Authority lists a lower 3% tax rate for small enterprises under specific conditions, including factors such as revenues and number of employees.
This rate should not be assumed automatically. A small company should check whether it meets all current conditions before using the 3% rate. The company may need to confirm:
Annual revenue level
Employee count
Legal form
Ownership structure
Activity type
Whether it has complied with tax registration
Whether accounts and records are complete
Whether the company is part of a larger group
Whether the Tax Authority accepts the small-enterprise treatment
For expats, the practical rule is simple: budget for 15% unless your accountant confirms that the company qualifies for the 3% regime.
Oil and Gas Corporate Tax
Oil and gas exploration companies are treated differently from normal commercial companies. The Oman Tax Authority lists 55% income tax for oil and gas exploration companies, based on concession contracts with the government.
This is mainly relevant for companies operating under petroleum concession arrangements. It does not normally apply to ordinary service companies, trading LLCs, consulting businesses, retail companies, or small expat-owned businesses unless they are directly within the applicable oil and gas exploration tax framework.
Businesses serving the energy sector should still get advice because subcontracting, foreign services, permanent establishment exposure, and withholding tax can create tax issues even when the company itself is not taxed at the oil and gas exploration rate.
Oman Tax Registration
Registration follows incorporation, which is handled on the register a company in Oman page. Tax registration is mandatory for businesses operating in Oman. The Oman Tax Authority states that income tax registration is required for any establishment engaged in economic activity in Oman within 60 days from the start of activity or from registration with the Ministry of Commerce, Industry and Investment Promotion, whichever applies.
This applies to newly registered companies as well as operating establishments. Registration is not optional just because the business has not yet made a profit.
Tax registration usually involves:
Commercial Registration details
Taxpayer details
Company activity
Legal form
Address
Contact details
Authorized representative
Financial year
Shareholder or beneficial ownership data where relevant
Tax portal access
A company should complete tax registration early because it affects tax filing, VAT registration, tax certificates, bank compliance, and future renewals.
Oman Corporate Tax Return Deadline
Oman companies must submit income tax returns electronically. The Tax Authority states that the income return for any tax year must be submitted before the end of four months from the end of that tax year or accounting period.
For example, if a company’s financial year ends on 31 December, the income tax return deadline is normally before the end of April of the following year. If the company has a different accounting year, the four-month deadline is calculated from that year-end.
The tax return process usually requires:
Financial statements
Revenue records
Expense records
Bank statements
Payroll records
Fixed asset register
Tax depreciation schedule
Related-party transaction details
Withholding tax records
VAT reconciliation, if applicable
Auditor-signed accounts where required
Tax return preparation should not start in the final week before the deadline. Missing invoices, unclear bank deposits, owner withdrawals, and undocumented expenses can all create problems.
Tax Payment Deadline and Late Payment
Tax due under the income return must be paid by the statutory deadline. The Oman Tax Authority states that tax due from the income return is payable by the identified return deadline. If tax is not paid, an additional tax of 1% per month is imposed on the unpaid tax due and payable.
The Tax Authority FAQ also states that failure to submit the income tax return can lead to a penalty of not less than OMR 100 and not exceeding OMR 2,000.
Businesses should plan for:
Filing deadline
Payment deadline
Cash availability
Bank processing time
Approval by owners or directors
Tax portal access
Accountant or auditor availability
Penalty exposure
A profitable company can still create tax problems if it does not set aside cash for tax.
How Taxable Income Is Calculated
Corporate tax in Oman is charged on net taxable income, not total revenue. This means a company is taxed on profit after allowable deductions and tax adjustments, not on gross sales.
A simplified calculation looks like this:
Item | Example |
|---|---|
Revenue | OMR 100,000 |
Deductible expenses | OMR 70,000 |
Accounting profit | OMR 30,000 |
Tax adjustments | Depends on law |
Net taxable income | OMR 30,000, if no adjustment |
Corporate tax at 15% | OMR 4,500 |
The final taxable income may differ from accounting profit because some expenses may not be deductible, some depreciation may be adjusted, and some income may be exempt or treated differently.
Common deductible expenses may include:
Salaries
Rent
Utilities
Business travel
Professional fees
Marketing costs
Office costs
Insurance
Bank charges
Depreciation under tax rules
Approved business expenses
Common risk areas include:
Personal expenses paid by the company
Owner withdrawals
Cash expenses without invoices
Related-party charges
Management fees to foreign entities
Unsupported travel expenses
Non-business entertainment costs
Unclear consultant payments
Vehicle expenses without business support
Good accounting reduces tax risk more than last-minute tax planning.
Example of Oman Corporate Tax Calculation
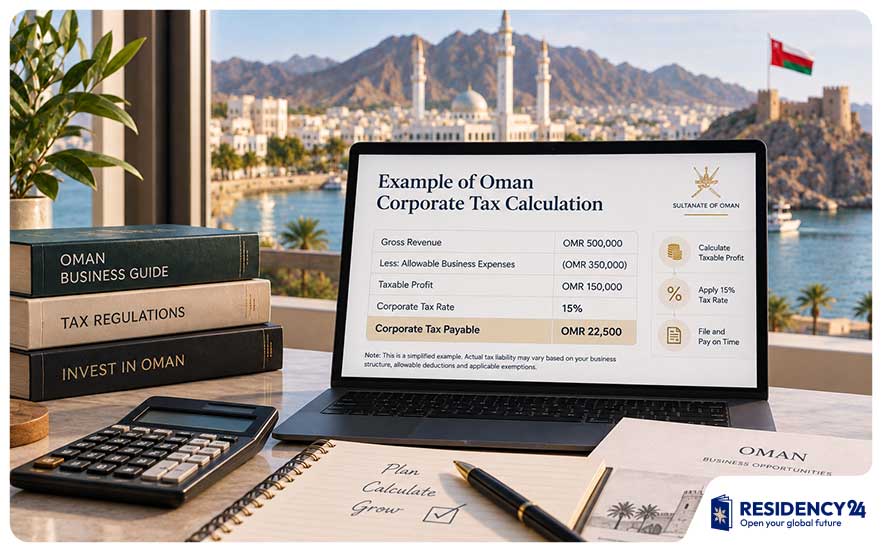
Assume an Oman LLC has annual revenue of OMR 180,000 and deductible expenses of OMR 120,000. Its taxable income is OMR 60,000 if there are no further adjustments.
Item | Amount |
|---|---|
Annual revenue | OMR 180,000 |
Deductible expenses | OMR 120,000 |
Taxable income | OMR 60,000 |
Corporate tax rate | 15% |
Corporate tax payable | OMR 9,000 |
If the company qualifies for the 3% small-enterprise rate, the tax treatment may be different. But that lower rate should only be used when eligibility is confirmed.
For planning, companies should also consider VAT, withholding tax, payroll, social insurance obligations for Omani employees, audit fees, accounting fees, and licensing renewal costs. Corporate tax is only one part of the business cost.
Oman Withholding Tax
Oman applies withholding tax on certain payments made to foreign persons or companies that do not have a permanent establishment in Oman. The Tax Authority states that withholding tax is imposed on certain Oman-generated income for foreign persons without a permanent enterprise in Oman, and the Omani payer must deduct tax at 10% of the gross amount and submit it to the authority no later than the 14th day after the end of the month in which the payment was made or credited.
The Tax Authority’s tax-rate page lists withholding tax at 10% on payments to non-residents for services, interest, or royalties.
Withholding tax can matter when an Oman company pays foreign suppliers for:
Services
Royalties
Software-use rights
Interest
Management fees
Technical support
Consultancy fees
Cross-border service contracts
Double tax treaties may reduce or modify withholding tax treatment. The Oman Tax Authority publishes double tax agreement information and a summary of withholding tax rates under Oman tax treaties.
Before paying a foreign supplier, the company should check whether withholding tax applies and whether treaty relief is available.
VAT and Corporate Tax Are Different
VAT is separate from corporate income tax. Corporate tax is charged on profit. VAT is charged on taxable supplies of goods and services.
Oman’s standard VAT rate is 5%. The Tax Authority lists the basic VAT rate as 5%, with zero-rating for certain goods and services such as exports, essential goods, and international transport, and exemptions for some activities including financial services and rental of residential properties.
VAT registration is also separate. The Tax Authority registration page states that VAT registration is mandatory when the business reaches the required threshold and optional at the lower voluntary threshold; the same page lists OMR 38,500 as the mandatory threshold and OMR 19,250 as the optional threshold.
A company may owe corporate tax even if it is not VAT-registered. A company may also be VAT-registered even in a low-profit year if its taxable supplies exceed the VAT threshold.
Corporate Tax and Free Zones
Zone choice changes the tax position materially, exactly as it does in the UAE - Free Zone vs. Mainland in Dubai explains the trade-off. Oman free zones and special economic zones can offer tax incentives, but a free-zone company is not automatically outside the tax system. The exact treatment depends on the zone, activity, formal approval, exemption period, and compliance conditions.
Oman’s OPAZ framework promotes special economic zones and free zones with incentives such as foreign ownership, customs advantages, profit repatriation, and tax exemptions. OPAZ states that zones can offer tax exemptions for up to 30 years, 100% foreign ownership, full repatriation of capital and profits, and zero import or re-export duties.
The 2025 Law of Special Economic Zones and Free Zones also creates a legal framework for tax exemptions, while excluding some activities from exemption, including banks, financial institutions, insurance and reinsurance companies, telecommunications enterprises, construction companies, and land or maritime transportation companies in the zone.
The key point: free-zone tax incentives should be verified before setup. A company may still need tax registration, accounting records, returns, VAT documentation, customs records, and exemption applications.
Oman Corporate Tax for Expats
Expats who own businesses in Oman should separate their personal immigration status from the company’s tax obligations. An investor visa, residence card, or foreign shareholder status does not remove the company’s corporate tax duties.
An expat-owned company may need to handle:
Commercial Registration
Investment license, if applicable
Tax registration within 60 days
Bookkeeping
Corporate income tax filing
VAT registration if threshold is reached
Withholding tax on foreign payments
Payroll documentation
Audit requirements
Bank account KYC
Ultimate beneficial owner information
Annual renewals
Tax certificates and clearances
For expats, the most common mistake is assuming that a newly registered company has no tax obligations until revenue is high. In Oman, tax compliance starts early, even if actual tax payable is low or zero.
Corporate Tax for Branches of Foreign Companies
A branch of a foreign company is generally taxed on Oman-source income or income attributable to its permanent establishment in Oman. The tax treatment depends on the branch’s activity, contracts, local presence, and whether a double tax treaty applies.
A foreign branch should review:
Whether it has a permanent establishment in Oman
Revenue attributable to Oman
Direct and indirect expenses
Head office charges
Cross-border service fees
Withholding tax
Transfer pricing
Tax treaty relief
Audit requirements
Return filing obligations
Branches often create more tax complexity than a simple local LLC because they connect the Oman operation to a foreign head office.
Permanent Establishment Risk
A foreign company can create tax exposure in Oman if it has a permanent establishment. This can happen when a foreign business has a fixed place of business, local operations, dependent agents, contracts performed in Oman, or other taxable presence depending on the facts and treaty position.
Permanent establishment risk can arise from:
Local office
Long-term project site
Construction or installation activity
Local employees
Local dependent agent
Repeated service delivery in Oman
Contract negotiation or conclusion in Oman
Equipment or facility use
Branch-like operations without registration
A foreign company selling into Oman should not rely only on “we are not registered there.” The substance of activity can create tax exposure.
Transfer Pricing and Related-Party Transactions
Transfer pricing is relevant when an Oman company deals with related parties, such as a parent company, shareholder, sister company, offshore service company, foreign management entity, or group IP owner.
Related-party transactions may include:
Management fees
Technical service fees
Royalties
Interest
Cost allocations
Shared staff expenses
Software charges
Trademark fees
Intercompany loans
Goods purchased from group companies
Back-office support fees
Oman has adopted Country-by-Country reporting requirements for large groups. PwC states that Oman introduced CbC reporting requirements applicable for reporting years beginning on or after 1 January 2020.
Even smaller companies should keep commercial support for related-party payments. If an Oman LLC pays a foreign shareholder for “consulting,” the payment should be documented, priced reasonably, and reviewed for withholding tax.
Pillar Two and Multinational Groups
Oman has implemented rules connected to the global minimum tax framework for large multinational groups. Royal Decree 70/2024 issued the Law of the Top-Up Tax on Constituent Entities of Multinational Groups, effective from 1 January 2025.
This does not affect most small and medium companies. It is mainly relevant to multinational enterprise groups within the global minimum tax framework. The Central Bank of Oman’s 2024 annual report described Oman’s measure as establishing a Domestic Minimum Top-Up Tax and Income Inclusion Rule for multinational enterprise groups with consolidated global revenues of at least EUR 750 million in at least two of the previous four fiscal years, aiming at a 15% minimum effective tax rate on Oman profits.
For ordinary expat-owned SMEs, this is usually not relevant. For multinational groups using free-zone incentives, group structures, or cross-border arrangements, it can matter.
Corporate Tax and Personal Income Tax
Corporate tax is separate from personal income tax. Oman historically did not have a broad personal income tax, but that is changing for higher-income individuals from 2028.
Oman issued Royal Decree No. 56/2025 on Personal Income Tax. The Tax Authority states that the law applies to natural persons whose total annual income exceeds OMR 42,000, with a 5% tax rate on taxable income, and enters into force at the beginning of 2028.
This matters for company owners because they should separate:
Company profit
Director salary
Owner drawings
Dividends or distributions
Personal income
Employment income
Foreign income
Family income
Tax residence
A company may pay corporate tax, while the owner may also have future personal tax considerations if income exceeds the personal income tax threshold after the law enters into force.
Oman Corporate Tax vs UAE Corporate Tax
Headline rates only tell part of the story; setup and running costs matter too - Business Setup Cost in Dubai gives the other side. Oman and the UAE now both have corporate tax systems, but they are different. Oman’s standard corporate tax rate is 15%. The UAE introduced a federal corporate tax regime with different rules, including a standard 9% rate above a threshold and a special free-zone framework.
For investors comparing Oman and Dubai, the difference is not only the headline tax rate. Oman may offer lower operating cost in some sectors and zone incentives for industrial, logistics, and free-zone projects. Dubai may offer a larger market, more free zones, stronger global connectivity, and a deeper business ecosystem.
Factor | Oman | UAE / Dubai |
|---|---|---|
Standard corporate tax rate | 15% | Lower headline standard rate in many normal cases |
Market size | Smaller | Larger |
Free-zone incentives | Strong in specific zones and activities | Strong but more complex after UAE corporate tax |
Best for | Industrial, logistics, Oman-market and lower-pressure operations | Regional HQ, services, ecommerce, trade, global access |
VAT | 5% | 5% |
Personal income tax | Starts in Oman from 2028 for high earners | No personal income tax on individuals currently |
The better jurisdiction depends on market access, cost, substance, banking, tax, and visa needs, not only the corporate tax rate.
Tax Deductions and Business Expenses
Oman companies should keep clear records for every business expense they want to deduct. The practical tax question is whether an expense is business-related, properly documented, and allowable under the law.
Common business expenses include:
Office rent
Utilities
Salaries
Employer costs
Professional fees
Accounting
Audit
Legal advice
Marketing
Software
Travel for business
Vehicle costs
Insurance
Bank charges
Repairs and maintenance
Depreciation
Approved subcontractor costs
Riskier expense categories include:
Cash payments
Personal travel
Family expenses
Entertainment
Owner lifestyle expenses
Unsupported consultant fees
Related-party charges
Payments to offshore entities
Mixed-use vehicles
Undocumented petty cash
A tax-efficient company is not one that hides income. It is one that records legitimate business expenses properly.
Accounting and Audit Requirements
Corporate tax compliance depends on proper accounting. A company should maintain books from the first day of activity, even before it becomes profitable.
Records should include:
Sales invoices
Purchase invoices
Bank statements
Receipts
Payroll records
VAT records, if registered
Contracts
Fixed asset register
Loan documents
Shareholder transaction records
Inventory records
Import/export documents
Withholding tax records
Financial statements
PwC notes that annual income tax returns should be accompanied by audited accounts signed by an auditor registered in Oman.
Small companies should check whether audit requirements apply to their legal form, capital, activity, bank requirements, or tax filing status. Even when full audit is not the main issue, clean accounting is still essential.
Corporate Tax for Free Zone Companies
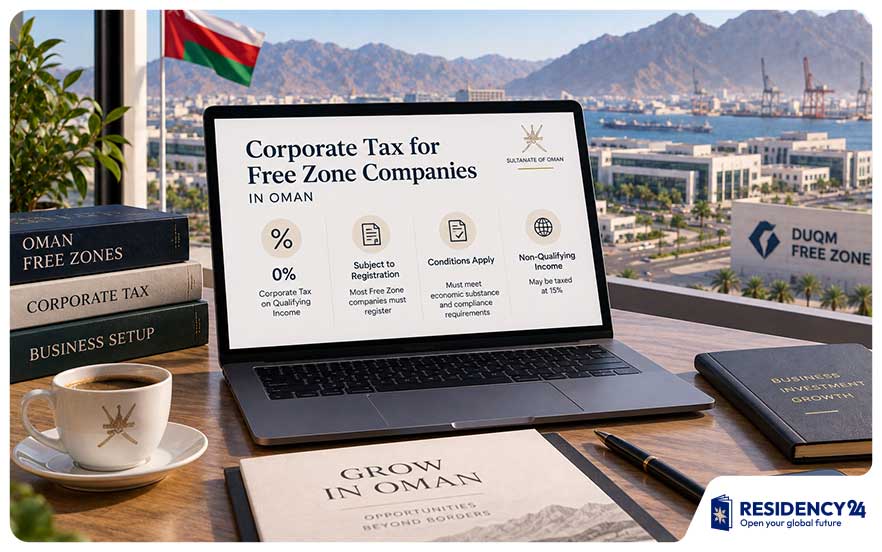
A free-zone company should not assume that “tax exemption” means no tax filing. Free-zone incentives usually depend on meeting zone conditions, holding the right license, and maintaining proper compliance.
A free-zone company should check:
Is the activity eligible for exemption?
Has the exemption been formally approved?
What is the exemption period?
Are there Omanisation conditions?
Are there substance requirements?
Are local-market sales taxable?
Does VAT zero-rating apply?
Are customs rules being followed?
Are records maintained?
Is withholding tax relevant?
Are returns still required?
The 2025 free-zone law framework and OPAZ incentives are useful, but they do not replace accounting, tax registration, and legal review.
Corporate Tax for Real Estate Companies
Real estate companies in Oman should review tax treatment carefully. A company holding property, renting property, developing property, or managing property may have different tax and VAT considerations.
Relevant issues include:
Rental income
Property management fees
Development profit
Construction contracts
Sale of property
VAT treatment
Residential vs commercial property
Municipal tax on rents
Transfer fees
Service charges
Interest expense
Depreciation
Withholding tax on foreign services
Related-party management fees
PwC’s Oman tax summary notes that residential property rental is exempt from VAT and that municipal tax applies to property rents at 3%.
A property company should not treat all real estate income the same way. Residential, commercial, tourism, and development activity can create different tax results.
Corporate Tax for Consulting and Service Companies
Consulting and service companies often have lower physical costs but higher cross-border tax issues. Many expat-owned Oman companies pay foreign contractors, software providers, agencies, or related parties abroad.
Key tax issues include:
Correct revenue recognition
Deductibility of contractor payments
Withholding tax on foreign service payments
VAT on local services
Reverse-charge or import-of-service analysis where relevant
Related-party fees
Owner salary vs profit distribution
Documentation of deliverables
Source of income
Permanent establishment risk in other countries
A consulting company with low expenses and high margins should set aside tax cash early because the 15% tax can become a real year-end cost.
Corporate Tax for Trading and Import Companies
Trading companies need to coordinate corporate tax with VAT, customs, inventory, and foreign supplier payments.
Tax issues for trading companies include:
Cost of goods sold
Customs documentation
Inventory valuation
Import VAT
Output VAT
Foreign supplier payments
Withholding tax on foreign services
Freight and insurance
Bad debts
Stock write-offs
Related-party purchases
Currency exchange differences
Bank finance costs
Trading companies often have high revenue but lower margins. This makes correct accounting important because errors in inventory or cost of goods can distort taxable profit.
Corporate Tax for Startups
Startups in Oman should not ignore tax because they are young or loss-making. Losses, investor funding, founder expenses, and early contracts all need records.
Startups should track:
Founder loans
Share capital
Investor funding
Convertible instruments, if any
Software costs
Salaries
Contractor invoices
Intellectual property
Foreign service payments
VAT threshold
Losses
Grants or incentives
Related-party transactions
A startup with no profit may still need to file a tax return. Failing to file can create penalties even if no tax is due.
Tax Planning for New Companies in Oman
New companies should plan tax at setup stage, not after the first year. The company’s activity, ownership, address, accounting year, VAT position, contracts, and bank account all affect tax.
A practical setup plan:
Choose the correct legal structure.
Register the company.
Register with the Tax Authority within 60 days.
Choose an accounting year.
Set up bookkeeping.
Separate personal and business bank accounts.
Check VAT threshold.
Review withholding tax on foreign payments.
Keep invoices from the first transaction.
Review contracts before signing.
Identify related-party transactions.
Set aside tax cash monthly or quarterly.
File the annual return before the deadline.
Pay tax on time.
Keep records for future audit or tax review.
Good tax planning is basic compliance done early.
Common Corporate Tax Mistakes in Oman
Many companies create tax problems through weak administration rather than aggressive planning.
Common mistakes include:
Not registering for tax within 60 days
Missing the four-month return deadline
Assuming no profit means no return
Not keeping invoices
Mixing personal and company expenses
Ignoring VAT registration threshold
Not deducting withholding tax on foreign payments
Treating free-zone status as automatic exemption
Not documenting related-party payments
Paying owner expenses through the company
Not reconciling bank deposits with invoices
Using cash without records
Filing without checking tax adjustments
Not budgeting for the 15% tax
Not using a qualified accountant or auditor where needed
The safest system is simple: record every transaction, classify it correctly, and file on time.
Oman Corporate Tax Checklist
Before the end of each financial year, companies should complete this checklist:
Confirm tax registration is active.
Confirm accounting records are complete.
Reconcile bank accounts.
Reconcile revenue with invoices.
Check expense invoices.
Review fixed assets.
Review payroll.
Review related-party transactions.
Review foreign payments for withholding tax.
Check VAT registration threshold.
Reconcile VAT returns if registered.
Prepare financial statements.
Arrange audit if required.
Calculate taxable income.
Set aside tax payment.
File return electronically.
Pay tax before the deadline.
Keep confirmation of filing and payment.
This checklist is useful for small companies, expat-owned LLCs, and foreign branches.
When to Get Tax Advice
Structure, licence and residency decisions interact: Residency24 works across company formation, residency, property purchase and investment planning. A simple local business with clean accounts may only need a competent accountant. A more complex company should get tax advice before filing or before signing major contracts.
Get professional advice if:
The company is foreign-owned
The company is in a free zone
The company pays foreign suppliers
The company receives income from outside Oman
The company has related-party transactions
The company has a foreign branch or parent
The company imports or exports goods
The company may cross the VAT threshold
The company has losses
The company has property income
The company operates in oil, gas, finance, insurance, telecom, construction, or regulated sectors
The company is part of a multinational group
The company may fall under Pillar Two rules
The company wants to use the small-enterprise rate
Tax advice is cheaper before a mistake than after an assessment.
Conclusion
Oman corporate tax is generally charged at 15% of net taxable income for institutions and commercial companies. A 3% rate may apply to qualifying small enterprises under specific conditions, while oil and gas exploration companies may be taxed at 55% under concession-based arrangements. Any business operating in Oman must register with the Tax Authority within 60 days from starting activity or company registration, file income tax returns electronically, and pay tax by the statutory deadline. The annual return is generally due within four months after the end of the financial year, and late payment can trigger an additional 1% per month on unpaid tax. Companies should also check VAT registration thresholds, withholding tax on foreign payments, free-zone exemption conditions, accounting and audit duties, and future personal income tax implications for owners. For expats and foreign investors, the safest approach is to treat Oman as a structured tax jurisdiction, not a tax-free business setup location.